I’m going to give you some blunt honesty about being an investor in gold stocks.
If you’re only investing because you assume or believe the price of gold is going higher, you’re likely making a mistake.
The success or failure of individual gold stocks rarely hinges on the timing of buying them before gold surges in price.
It’s just not how the biggest gains manifest in this sector.
And I understand why it seems counterintuitive. Investors want there to be a single factor catalyst – a binary reaction of gold go up = stocks go up. It’s simple and it makes your decision tree simple.
But it’s just not the case.
If you’ve been a gold stock investor for any time at all, you should be familiar with the fact that much of the time, there’s a disconnect between how gold stocks behave, and what the price of gold is doing.
For example, take a look at this performance chart comparing Newmont (NYSE: NEM) to the price of gold (represented by the gold ETF NYSE: GLD).
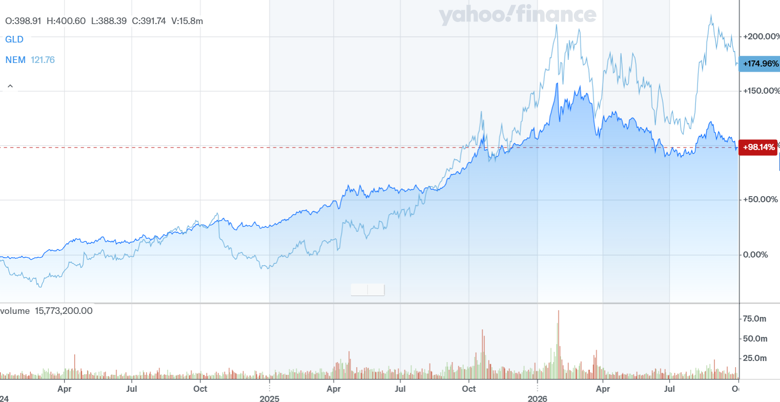
Newmont goes from wildly underperforming gold’s moves for most of 2024-2025, to then wildly outperforming since late 2025. The up or down trends don’t even match up very evenly and certainly not predictably.
I chose to use Newmont for this example because it’s one of the top performing gold majors in the market. But there are other majors (anything getting close to $10 billion market cap is major territory) that have underperformed gold during this period.
Take a look at this chart of B2Gold (NYSE: BTG):
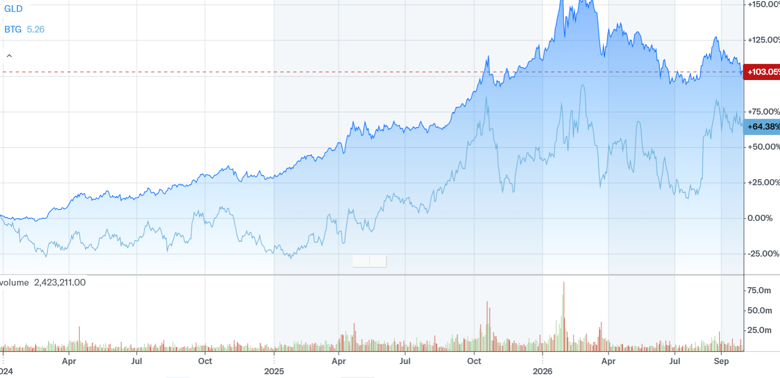
B2Gold is still lagging gold. It’s a $7 billion company with multiple projects.
I hope it’s obvious, but the details of what’s going on with those projects is much more important for B2Gold’s share price than whatever has been happening with the price of gold.
That’s true for ALL gold miners! And maybe B2Gold is now undervalued – but it’s not because of what’s going on with the price of gold – it will be because of the value of the projects the company operates. Higher gold prices only benefit companies that can and do develop and run mines efficiently and profitably.
More to the point: if you’re buying a gold miner, developer or explorer where some sky high gold price is the single catalyst for success/failure then you are not likely to succeed.
There’s a gold price where IR firms will give you a case where any acre of cow pasture is a sure-thing bonanza. The media loves to talk about the fact that there’s trillions of dollars of gold in the ocean or in asteroids.
These kinds of deposits are just not economical to mine unless gold is $1 billion/oz – but in a scenario where gold is that expensive, the cost of the diesel needed to mine it would make it unaffordable to do so.
So you would need to live in a world where inflation makes gold expensive but not oil.
That world doesn’t exist.
In the real world of gold stock investing, there are a few ways to see big gains.
- Buy very early stage explorers, and ride out the small percentage of them that turn into tier-1 deposits.
- Own royalty firms for the long haul, compounding your wealth by reinvesting dividends for years.
- Buy small developers that are likely takeover candidates.
Numbers 1 and 2 can take a while. Only the 3rd option can bring substantial gains relatively quickly.
And right now, I’m about to add what I’m calling “The Next Buyout” company to my Golden Portfolio IV service.
The company will be added tomorrow, October 1st.
We don’t know what’s going to happen with gold’s price, but we do know that gold majors always need to refill their mining capacity by buying up smaller companies.
That’s exactly what I’m predicting will happen.
And it all starts tomorrow.
Best,
Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio